All Categories
Featured
Future Middle East Market Trends for 2026 Global Markets
Building Sustainable Financial Portfolios with GCC Securi...

Ways to Leverage International Capital Potential in 2026
How Economic Diversification Drives GCC Stability for 2026
Table of Contents
Although all GCC countries deal with the obstacle of guaranteeing future work for nationals while preserving reliance on foreign employees to fill particular roles, the urgency of this issue differs across national contexts since GCC countries' demographics and concern areas diverge significantly. For countries that rely heavily on foreign labour, there is a threat that transition processes will worsen bad working conditions and increase employees' vulnerability to exploitative practices.
Labour reforms in Qatar, for example, abolishing the controversial labour sponsorship system (Kafala); and presenting a base pay, are significant examples of reform. Economic diversification and related green shift strategies create ample opportunities but also boosted obligations for companies running in the GCC region. Throughout this procedure, both governments and services have a responsibility to regard and advance worker well-being and represent future labour requirements through, for example, ensuring good working conditions and investing in filling future skills spaces.
Key Foreign Capital Prospects for the GCC MarketWhereas federal governments are needed to supply robust regulative structures and enforcement mechanisms in line with international requirements, services have an obligation to respect worldwide acknowledged human rights and labour requirements in line with the UN Guiding Principles on Business and Human Rights. Organizations can likewise utilize their utilize to make sure that governments and partners reinforce policies and accountability mechanisms, supplying an environment conducive to responsible business practices.
Expecting this risk and building capability around how to fix this problem within the GCC context will be essential to promoting accountable business in the region.
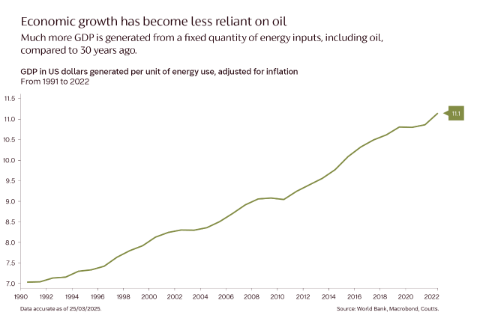
For decades, hydrocarbon profits formed the political economy of the Gulf Cooperation Council (GCC). In 2010, oil and gas accounted for more than 70% of federal government incomes throughout many GCC states. Today, that figure is steadily decreasing not because oil has actually ended up being unimportant, however since diversification has moved from aspiration to execution, Invest-Gate reports.
Essential Global Investment Opportunities across GCC Market
The UAE's non oil sector broadened by more than 6% in 2023. It is a structural transformation redefining financial influence and capital allocation in the region.
Oman and Bahrain have actually pursued fiscal combination and logistics driven diversification. These techniques operate as economic operating systems collaborating policy, capital implementation, infrastructure development, and foreign financial investment destination.
The UAE brought in more than $22 billion in FDI inflows in 2023, ranking amongst the leading worldwide receivers. QatarEnergy dedicated over $30 billion to LNG growth while parallel investments flowed into technology and sovereign portfolios abroad. Facilities, tourism, innovation, renewable resource, and logistics are now absorbing capital once focused in upstream oil tasks.
Strategies for Asset Allocation for 2026 Global Markets
Diversity is not only financial it is geopolitical. Financial power is increasingly measured by: Control over worldwide logistics passages Sovereign wealth fund influence in global markets Technological environments Ability to attract international talent The UAE has actually positioned itself as a global financial and logistics hub. Saudi Arabia is leveraging scale and domestic demand to reshape local supply chains.
As non-oil sectors broaden, fiscal resilience enhances. Recover cost oil costs have actually gradually declined in some GCC states due to diversified profits streams, consisting of barrel, corporate taxes, and financial investment income. Capital streams within the area are likewise altering. Riyadh is emerging as a local headquarters center following Saudi localization guidelines.
Top Foreign Capital Trends across GCC EconomySaudi Arabia led the region in IPO proceeds in 2023-2024, while the UAE continues to dominate in startup funding and tech ecosystem maturity. This redistribution of financial gravity is slowly recalibrating local influence.
Role of Capital on GCC Industrial Transformation
The GCC is not moving "away" from oil it is moving beyond reliance on it. The strategic shift lies in transforming oil wealth into varied economic power.
The improvement underway is redefining both local hierarchy and global capital combination.
Sweeping modifications are coming to countries in the Gulf Cooperation Council (GCC). The United Arab Emirates (UAE) and the Kingdom of Saudi Arabia (KSA), long reliant on hydrocarbon exports, are charting a strong new course toward financial diversity. Regional production and production are at the leading edge of the shift, together with blossoming sectors, including tourist, retail, and technology.

Latest Posts
Benefits of Diversified Capital Allocation in 2026

Future Middle East Market Trends for 2026 Global Markets

Building Sustainable Financial Portfolios with GCC Securities